FUEL ONLINE / Fintech Companies / Industry growth plan
Fintech Marketing
Fintech growth gets noisy when product research, consumer questions, and technical evaluation are treated as the same demand. Fuel builds a fintech marketing program around use case, company profile, market, integration need, and buying role. We connect decision pages, approved proof, channel priorities, and the inquiry path, then use sales team feedback to improve fit. The goal is accepted product demos, with work prioritized against evidence and operating capacity rather than traffic alone.
Product category and markets served; Buyer role, company size and sales cycle; Regulatory review ownership; Demo acceptance and pipeline definitions
Market the buyer’s evaluation, not just the product category
Fintech marketing should identify who buys the product, who evaluates it and what each person needs to decide. Fuel Online can connect that buying-team map with positioning, search architecture and acquisition campaigns. The commercial aim is a relevant evaluation or sales conversation, supported by the product’s actual capabilities rather than broad financial technology language.
Begin with the real buyer and business use case. A finance leader, operations team, developer and procurement reviewer may enter the same opportunity with different questions. The main page should explain the product’s purpose, while supporting pages answer distinct evaluation tasks. Avoid expecting a single feature list to persuade every participant.
| Evaluator | Useful decision content | Commercial handoff |
|---|---|---|
| Business owner of the problem | Actual use case, workflow and product scope | Relevant discovery conversation |
| Technical evaluator | Verified integration information and documentation route | Technical evaluation through the proper team |
| Commercial reviewer | Approved buying process and relationship information | Qualified procurement or sales discussion |
Explain the workflow before adding category jargon. Show what the product does, who uses it and where it fits in the customer’s current process. Use verified product information for integration, security or regulated-service claims. If an answer depends on a particular configuration or agreement, make that boundary clear instead of publishing an unlimited promise.
Proof should match the evaluation question. An authorized customer example can show the use case and the company’s role. Documentation can clarify implementation. A genuine team or company profile can help a buyer understand who stands behind the product. Do not invent adoption figures, savings or compliance status to fill a proof gap.
Design the destination before choosing the channel
Ask an agency to show the page or asset that will receive each audience. A demand campaign for a specific use case needs more than a generic homepage. Technical research may need a clear route into existing documentation rather than another promotional article. Every proposed destination should have a distinct job in the buying process.
Product and service boundaries matter. If the company serves businesses, avoid consumer messaging that creates unrelated account questions. If the product has multiple audiences, make their routes explicit. Qualified demand can be lost when a relevant visitor cannot tell which offering or sales team applies.
Agree who owns updates to product facts. Fintech offers can change, and the agency should have a reliable approval route for capabilities and commercial terms. Marketing can preserve a stable structure while specific facts are maintained by the responsible product and business teams.
Measure evaluation progression
Track relevant inquiries, discovery meetings, accepted evaluations and subsequent commercial stages using the company’s definitions. Distinguish developer support, existing customer requests and unrelated consumer questions from new buying demand. A high contact count can conceal a weak audience match.
Review broad reasons opportunities do not progress. Missing functionality, unsuitable buyer type, unclear implementation expectations and sales follow-up delays require different responses. The agency should connect its recommendation to the observed pattern rather than treat every loss as a need for more traffic.
A useful pilot chooses one real use case and a defined buying audience. Improve the destination and handoff, record the launch and review opportunities with sales and product teams. Include the content or campaign that introduced the opportunity, but avoid claiming that a single touch caused the entire sale.
Expand to another use case when it has a distinct buyer problem and a supported product offer. Keep existing useful documentation and proof intact. This creates a coherent commercial site rather than a growing set of interchangeable technology pages.
Explore financial services marketing and SaaS marketing for related acquisition structures. Fuel’s fintech scope should make the buyer, use case and evaluation journey explicit.
Specify a product evaluation pilot that can actually launch
A fintech marketing pilot is easier to evaluate when the proposal identifies a buyer task, a product journey and a release that the team can inspect. For example, a business selling payment infrastructure to marketplaces could focus on the route from a marketplace use-case page into a relevant product demonstration. The pilot would explain which marketplace operating model the product supports, what a visitor needs to understand before requesting a demonstration and what context sales needs to prepare that conversation. This is an illustrative scope, not a statement about a particular product’s capabilities.
Ask the agency to write the pilot acceptance record before it begins production. Include the starting page and contact route, intended audience, approved facts, responsible reviewers, implementation owner and evidence that will establish whether the release works. Useful acceptance checks might include a visitor reaching the correct demonstration route, submitted context arriving in the intended sales fields and the receiving team identifying the use case without reconstructing it from unrelated browsing history. These checks test the journey the agency controls; they do not establish that a visitor will become a customer.
Keep the first release small enough to diagnose. A use-case page, one supporting implementation explanation and a revised demonstration handoff can form a coherent pilot. Adding several unrelated audiences at once makes it harder to tell which change affected inquiry quality. The proposal should state which existing components will be reused, which require development and which depend on client product input. A working contact route matters more than an extensive list of assets that cannot yet be approved or connected.
Connect documentation versions with public product explanations
Fintech buyers may move between a marketing page, technical documentation, a sales presentation and a demonstration environment. Give each public capability statement a source of truth and an owner who can resolve differences between those surfaces. The agency’s content record can identify the product, applicable version or configuration, source document, reviewer and next review trigger. This is an editorial maintenance method; it does not substitute for the company’s technical, commercial or compliance approval process.
Consider an integration that becomes available for one configuration before it is available across the product. The marketing task is to communicate the supported scope precisely and direct the evaluator to the relevant documentation. Ask the agency to show how it would update the use-case page, campaign destination and sales handoff together. A broad headline should not silently outlive a narrower technical description. Where a product owner has not confirmed availability, the working draft can remain unpublished while other verified parts of the release proceed.
A practical change record distinguishes a wording correction from a changed product fact. A correction may require an editorial review; a changed integration, market or commercial offering may require different reviewers and several connected updates. Name the person who opens the change, the surfaces affected, the approval needed and the completion evidence. Store the previous approved copy so the team can explain what changed. The agency should maintain the marketing implementation record while the client retains authority over the underlying product facts.
Measure one opportunity across several evaluators
A buying team can generate several inquiries without representing several separate opportunities. Imagine a finance lead requesting a demonstration, a developer asking an integration question and a procurement participant requesting buying-process information from the same prospective customer. These interactions answer different questions. A useful reporting structure can retain the individual requests while associating them with the same commercial evaluation where the company’s systems and approved identity rules support that association. Do not add them together as three independent pipeline outcomes.
Agree which record is being counted in each report: a contact submission, a person, an account or an accepted opportunity. Keep those definitions beside the metric. Sales may associate several people with one opportunity while marketing still needs to understand which destination helped each person. Preserve both views rather than forcing every interaction into a single first-touch narrative. Unknown or unmatched records should remain visible as a data limitation rather than being assigned to a campaign by assumption.
The handoff can carry the declared company, buying role, use case and requested next step, using only information appropriate for the company’s approved collection process. Avoid asking a prospect to enter account credentials or sensitive transaction details into a general marketing inquiry. An existing-customer support request needs a useful support destination; it should not improve the apparent volume of new commercial demand. Have the receiving teams agree how misrouted requests are recorded and redirected without losing legitimate evaluation questions.
Review progression at the level where the decision occurs. A technical question resolved, a demonstration accepted and an opportunity advanced can be useful intermediate observations, but their meanings differ. If an evaluation pauses because the integration is unsuitable, changing advertisement copy will not create the missing capability. If an eligible buyer cannot find implementation information, a clearer documentation route may be a relevant marketing action. Record the observed reason and the proposed response together so the next release follows the actual constraint.
Make implementation responsibility visible in the agency proposal
Require an ownership plan that separates recommendation, implementation, approval and verification. For a revised demonstration form, an agency might design the fields and routing specification, a client developer might implement the connection, a sales operations owner might approve field mappings and both teams might verify the received test submission. The assignment can differ by organization. What matters is that the proposal names those responsibilities instead of treating a design file as a completed commercial journey.
The same distinction applies to content and measurement. Identify who publishes approved product wording, who updates documentation links, who configures campaign destinations and who maintains the agreed commercial stage definitions. Ask for the delivered artifacts: approved copy, destination map, routing specification, change log and a recorded verification result. A buyer should be able to tell which work is complete and which dependency remains with another team without interpreting a long activity report.
End the pilot review with a specific investment decision. Keep a release that improves the intended journey, revise a destination when evaluator questions remain unanswered or defer expansion while a product dependency is unresolved. Document the reason, owner and next evidence needed. This provides a practical basis for comparing fintech marketing agencies: the stronger proposal makes the evaluation journey, delivery responsibilities and commercial learning process inspectable before the company commits to a wider program.
AGGRESSIVE FROM THE START
One month. The work many agencies stretch across three.
Our mandate: move faster, go deeper and put experienced specialists to work immediately.
Fuel attacks the work in parallel: site audits, technical errors, new content, internal links, backlink outreach and conversion improvements. Your agreed scope determines the channels; urgent fixes do not wait behind a drawn-out planning phase.
The fintech marketing brief identifies visibility and lead barriers. Actionable fixes move into production while deeper analysis continues.
Your fintech marketing agency work runs alongside industry-specific content, relevant links and earned-authority outreach, based on your agreed scope.
The marketing for fintech companies review shows completed work, lead quality and the next opportunities. You see who owns each action.
Fast execution is the operating standard. Access, approvals and scope shape delivery; search and revenue results have their own timelines.
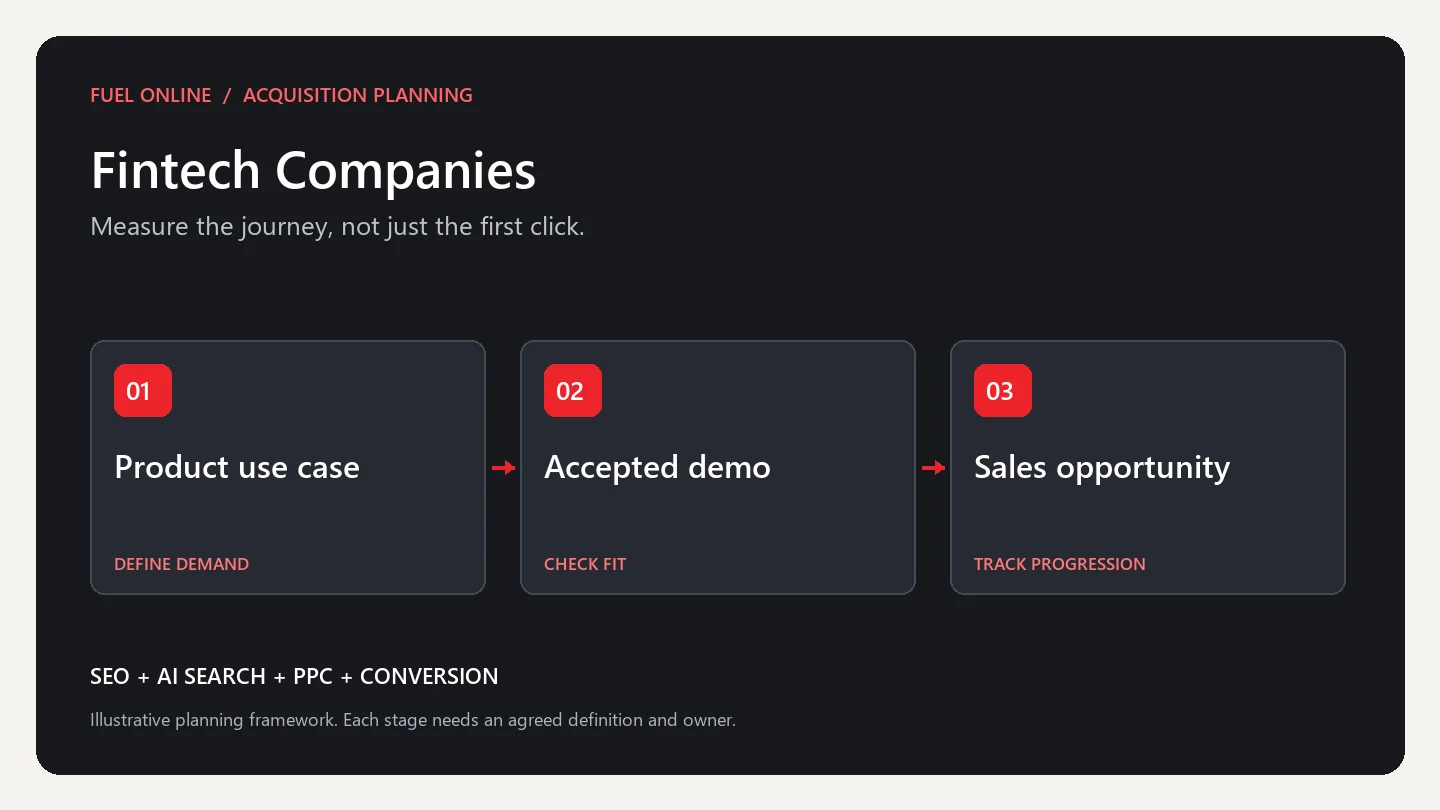
What fintech marketing changes for fintech demand
A useful fintech marketing plan starts with the commercial constraint. Fuel identifies which buyers the organization wants more of, what they need to believe before contact, and which requests consume time without a realistic next step. For fintech, the fit decision turns on use case, company profile, supported market, integration need, buying role, and implementation timing.
Fuel turns that definition into category, use-case, integration, implementation, and comparison pages, channel priorities, proof requirements, and a handoff that retains company, role, use case, market, integration context, and timing. Work that cannot be supported by approved product capabilities, current integration documentation, and permissioned customer evidence stays out of the public claim set.
A practical fintech hub diagnostic
Use this diagnostic when channel activity improves but the receiving team does not see a comparable change in accepted product demos. The diagnostic for fintech marketing starts with the observable symptom, checks the page, source, campaign, or handoff responsible for it, and ends with one reviewed action, owner, and validation method.
Observable symptom
Marketing activity rises, but the team still cannot tell why 'payment orchestration platform for marketplaces' inquiries are mixed with demand closer to 'personal loan calculator'.
What to inspect in fintech marketing agency
Review source, page, offer, contact path, and the final acceptance or rejection reason together.
Decision criteria for marketing for fintech companies
Prioritize the page, message, exclusion, or handoff with the clearest connection to unsuitable demand.
Inspectable output
A one-page fintech marketing decision record naming the symptom, evidence, owner, release, and measure tied to accepted product demos.
Marketing for fintech companies deliverables you can inspect
The team receives a demand map, evidence register, prioritized channel backlog, conversion specification, and commercial decision cadence it can inspect and own.
- Buyer and offer map, used to define the fintech marketing scope.
- Evidence and approval register, used to govern the fintech marketing agency release.
- Prioritized page and campaign backlog, used to evaluate the marketing for fintech companies decision.
- Conversion and routing specification
- Commercial scorecard and decision cadence
Illustrative fintech example
Illustrative example, not a client result: Fuel would compare the path taken by a marketplace payments buyer that needs orchestration and integration detail with the activity created by consumer calculator traffic with no product-evaluation intent. The decision is whether to fix the decision page, proof, contact path, or channel sequence before adding spend.
The fintech marketing agency work would produce a one-page demand map showing fit, friction, evidence, owner, and the next controlled release. The example becomes useful only when the team can trace the change to accepted product demos.
Within marketing for fintech companies, the buyer team can inspect the artifact, approval, and next investment decision.
How commercial progress is judged
Fuel connects page, query, campaign, or source context with acceptance, rejection reasons, response, capacity, and accepted demos, opportunity creation, sales-cycle stage progression, and pipeline by use case. Diagnostic measures explain where the journey breaks; they do not replace the business outcome.
The decision record for fintech marketing states what changed, why it changed, who approved it, and whether the next action is to expand, revise, consolidate, or stop.
Reporting for marketing for fintech companies must connect the service-specific diagnostic to accepted product demos, explain data limits, and name the next decision rather than treating activity as proof of value.
Questions to ask a fintech agency
Ask for the first demand map and channel decision, then confirm who owns pages, campaigns, tracking, approvals, and the handoff to the receiving team. A useful proposal explains which channel waits and why.
When reviewing fintech marketing, require a named practitioner, implementation owner, approval path, and sample artifact. Reject unsupported promises of rankings, citations, lead volume, cost, or revenue.
RELEVANT PUBLISHED WORK
A fintech acquisition example
The published Fuel Online B2B payment-processing case study reports cost per acquisition moving from $1,250 at baseline to $685 in month 3, a reduction of about 45%. The case combines paid search with semantic intent research.
Read the fintech PPC and GEO case study, including its baseline and measurement period. This is one reported engagement, not a forecast for your business.
How we measure fintech marketing agency
- accepted demos
- opportunity creation
- sales-cycle stage progression
- pipeline by use case
Separate inquiry volume from usable demand
Qualified-inquiry rate = inquiries meeting your agreed criteria ÷ total inquiries reviewed.
Illustrative arithmetic: 20 suitable inquiries out of 50 reviewed inquiries is a 40% qualified-inquiry rate. Record why the other 30 did not fit before increasing investment.
Agree on the baseline, data source and qualification criteria before comparing results. Separate visibility from inquiries and accepted business opportunities.
CONNECTED SERVICES
Choose the right next step for your business
Explore Fuel’s Industry growth plan capabilities, published campaign work and team to evaluate how we would support your organization.
BEFORE YOU CHOOSE AN AGENCY
Questions about fintech marketing agency
What will Fuel deliver in the first 30 days?
During the first month, the fintech marketing scope produces a demand map, evidence register, prioritized journey decision, and the owner of the first controlled release. Fuel also records the client inputs and approval needed for the first release.
What does Fuel need from our fintech team?
Effective fintech marketing agency work requires a commercial owner, account and page access, approved proof, acceptance criteria, capacity limits, and feedback from the receiving team. Fuel identifies missing access or ownership before work is scheduled around it.
How will we know the work is commercially useful?
Under marketing for fintech companies, commercial usefulness depends on whether the diagnostic connects to accepted product demos, the data limits are stated, and the evidence supports a clear keep, revise, or stop decision.
Should we invest in SEO or paid acquisition first?
Choose the channel that addresses the closest constraint to accepted product demos. In fintech marketing, paid acquisition can test active demand quickly, while SEO is better for durable decision pages; both wait if the offer, proof, contact path, or receiving capacity is the real problem.
What does a credible fintech marketing agency scope include?
A credible fintech marketing agency scope includes buyer-fit criteria, evidence governance, journey priorities, channel sequencing, conversion ownership, and a commercial decision cadence. It also names the client dependencies, practitioner, deliverable, and approval path.
How should marketing for fintech companies report commercial progress?
Reporting under marketing for fintech companies should connect the service-specific diagnostic to accepted product demos, show what changed and why, state data limits, and name the next decision.
Make your next agency conversation specific.
Show us where fintech demand becomes unclear between 'payment orchestration platform for marketplaces' and 'personal loan calculator'. The first working session on fintech marketing agency will identify the priority artifact, evidence, owner, and approval decision for accepted product demos.
Talk with a Fuel strategist →